Snap Finance

Screenshots
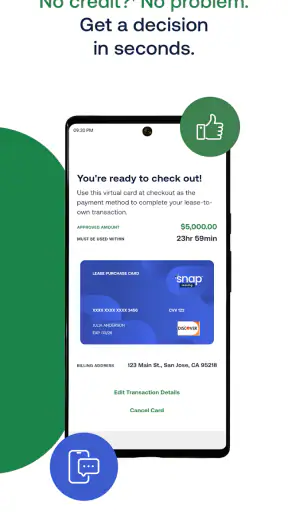
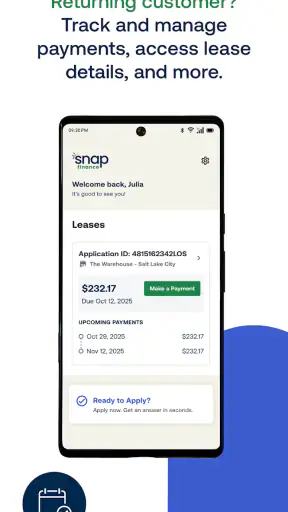
Details
- Rating
- 819.00 reviews
- Version
- 2.2.11632
- Developer
- Snap Finance
Analysis by Norviv
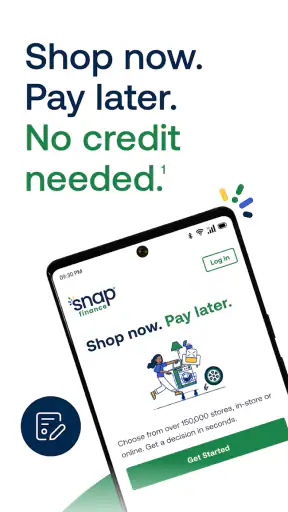
Buying something important can be stressful when the timing is wrong, and that is the situation Snap Finance is built around. I reviewed this shopping app as a way to explore a purchase-now, pay-later option without treating it like a magic solution to affordability. The central appeal is straightforward: the app from Snap Finance presents financing for shoppers who may not have a traditional credit history, with the store summary emphasizing that no credit is needed.
That promise makes the app interesting, but the real experience depends on more than the headline. You need a reliable connection at several points, you need to understand the repayment terms before accepting anything, and you need to be comfortable managing a financial commitment from your phone. I found it most useful as a focused tool for checking whether a planned purchase fits a particular payment arrangement, rather than as an excuse to shop more freely.
It is a free shopping app for everyone, and it runs on devices using Android 7.0 or later. The current release is version 2.2.11632. Its listing shows an average rating of 4.8 from around 9,200 ratings, with more than 500,000 installs, so it has attracted a substantial audience without being a general-purpose marketplace.
How Snap Finance feels when a purchase depends on a connection
I focus here on how a dependable connection affects each stage of using Snap Finance, from checking a purchase option to confirming what happened after an interruption. My practical rule is to treat connectivity as part of the decision, not just a technical detail: a steady session gives me room to review the commitment calmly, while a stalled screen is a reason to pause rather than rush ahead.
Getting started without confusing the app with the store
The first thing I would explain to a friend is that Snap Finance is not simply another place to browse products. It sits between shopping and financing. That distinction matters because the app is most valuable when you already have a reason to investigate a purchase and want to see whether a payment option is available to you.
The setup is easier to understand when you approach it with one specific goal. Instead of opening it casually and thinking about what you might buy, I would have the item, retailer, or planned expense in mind first. This keeps the experience practical and reduces the risk of treating available financing as extra spending power.
The app’s “no credit needed” positioning may appeal to people who have limited credit history or who do not want a conventional credit check to be the only gateway to a purchase. Still, that phrase should not be interpreted as “no financial review” or “no responsibility.” Any pay-later arrangement deserves the same attention as a normal bill: check the total obligation, the schedule, and what happens if your budget changes.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
One useful habit is to keep a note of your existing fixed payments before starting an application or purchase flow. That small preparation makes it easier to judge a new commitment honestly. A financing app can make a large price look smaller when divided into payments, but the full obligation remains relevant to your monthly budget.
Where connectivity changes the experience
Because this is a financing and shopping service, a network connection is especially important when information must be retrieved or submitted. Browsing account-related details, moving through an application, checking an offer, or completing a transaction can all become frustrating if the connection drops at the wrong moment. I would not begin a time-sensitive purchase while moving through an unreliable signal.
This is different from using a simple calculator or a saved shopping list. A finance app needs current information, and I would treat anything displayed during an interrupted session cautiously until the app reconnects and shows the complete state again. If a page appears incomplete, the safest response is to wait for the connection rather than repeatedly tapping buttons.
A practical mobile workflow is to open the app on a stable home or workplace connection, review the details carefully, and only then continue when you have enough time to finish. Public Wi-Fi can be convenient, but I would prefer a trusted network or mobile data for personal financial activity. The point is not speed; it is avoiding an uncertain session while entering sensitive information.
My main connectivity tip is simple: never treat a frozen screen as proof that a payment or application failed. First check whether the app has recovered, look for a clear confirmation, and avoid submitting the same action repeatedly. Duplicate attempts are an unnecessary source of confusion in any payment-related workflow.
Using it in everyday mobile situations
Snap Finance makes the most sense on a phone when you are already dealing with a purchase decision away from a desk. Imagine replacing a necessary household item while standing in a retailer, or checking a financing route after finding an eligible purchase during a busy day. The mobile format can save you from postponing the decision until you reach a computer.
That convenience has a trade-off. A phone encourages quick decisions, especially when you are in a store and want to finish the transaction. I found that the best approach is to separate the practical steps: identify the item, review the payment information, compare the commitment with your budget, and only then approve anything. The app can make the process accessible, but it cannot make an unaffordable purchase affordable.
A larger screen may be better when you need to read several details at once. On a phone, long terms can require scrolling, and it is easy to focus on the scheduled payment while overlooking the broader cost or conditions. I would rotate to a more comfortable setting, increase the text size if needed, and avoid reviewing an agreement while distracted.
Another realistic use is account checking between payments. Rather than waiting until a problem appears, I would make the app part of a regular money routine: open it when you have a reliable connection, review what is due, and compare that information with your personal budget. This is a more responsible use than opening it only when you want to make another purchase.
What happens when the network or session fails
Connectivity problems are not just an inconvenience here because the app deals with personal and financial actions. If a page does not load, I would first confirm whether other apps can reach the internet. If everything else is also offline, switching between screens will not solve the problem. Moving to a stronger signal or waiting for a trusted connection is more sensible.
If the connection fails after you press a button, do not immediately repeat the action. Close impatience out of the process. Reopen the relevant screen after the connection returns and look for a status, confirmation, or updated account information. If the result is still unclear, contacting Snap Finance through its official support route is safer than guessing.
There is also a distinction between a network failure and an app problem. If other services work normally but Snap Finance remains stuck, restarting the app can be a reasonable first step. I would avoid clearing information or uninstalling it in the middle of an unresolved transaction, because that can make it harder to reconstruct what happened on the device.
Keeping the app updated is another sensible recovery measure. The installed version shown for this review is 2.2.11632, and updates can matter for stability and compatibility. I would update over a dependable connection rather than starting an update just before entering a store or beginning a purchase.
For anyone asking whether the app is dependable during travel, my answer is cautious: plan around connectivity rather than assuming every step will work smoothly in a weak-signal area. Save the time to complete important actions when you are connected, and do not rely on an interrupted session for proof of a completed transaction.
Using less data without making the process risky
People on limited mobile plans may wonder whether a shopping and finance app will consume noticeable data. I would use it deliberately rather than leaving it open while browsing aimlessly. Start the app when you have a clear task, complete that task, and close it when you are finished. This is good for concentration as well as data use.
Wi-Fi is useful for account review and application steps, but network quality matters more than simply seeing the Wi-Fi symbol. A crowded or unstable connection can create the same uncertainty as weak mobile data. For sensitive actions, I prefer a connection that remains steady from the first screen through the confirmation stage.
Do not trade security for data savings. Avoid unknown networks just because they are free, and do not postpone important updates indefinitely. A better compromise is to use trusted Wi-Fi for routine app updates and account review, while using mobile data only when the task is urgent and the signal is reliable.
One non-obvious advantage of a focused workflow is that it helps you notice errors. When you open the app only for a defined purpose, you are less likely to overlook a loading problem or mistake a partially displayed screen for a completed step. Data-conscious use and careful financial use reinforce each other here.
Who will benefit, and who should choose another route
I can see Snap Finance helping shoppers who need to investigate a purchase-now, pay-later option and may not fit the usual credit-based path. It is also practical for someone who prefers handling financing from a phone instead of managing a paper-heavy process. The free download and broad age rating make it approachable for a wide range of adult shoppers who are responsible for their own payments.
I would not recommend it to someone who is already struggling with recurring bills, who cannot identify where the next payment will come from, or who is attracted mainly by the smaller appearance of installment amounts. In that situation, delaying the purchase, choosing a less expensive item, saving first, or speaking with a trusted financial adviser may be better.
It may also be the wrong choice if you want a simple budgeting app, a broad product comparison service, or a traditional credit card with a familiar rewards structure. Snap Finance has a narrower purpose. A bank app is usually better for viewing all accounts together, while a retailer’s own payment option may be easier when you are already committed to that retailer and its terms suit you.
The important comparison is not just “which app approves me?” It is “which option gives me the clearest total cost and the least chance of missing a payment?” A conventional purchase using money already set aside remains simpler. A standard credit product may provide different protections or flexibility, depending on the provider and agreement. Snap Finance is worth considering when its specific arrangement solves a real timing problem, not merely because it makes checkout possible.
Small habits that make the app safer to use
Before accepting anything, I would read beyond the prominent payment figure. Look for the complete schedule, the total amount owed, and any conditions that affect the arrangement. If a term is unclear, pause and seek an explanation before proceeding. A fast mobile flow is not a reason to skip the part that determines what you will actually pay.
I would also compare the planned payment with the date my income normally arrives. A payment that looks manageable in isolation can become awkward if it falls beside rent, utilities, or another fixed obligation. Matching the schedule to your real cash flow is one of the most useful checks you can make before committing.
Keep records of confirmations and important account information in a secure place. Do not rely solely on memory, especially if you use several payment services. If a confirmation screen appears, take note of the relevant details in a way that does not expose private information to anyone else using the phone.
Finally, treat the app as a tool for one decision at a time. The strongest use case is a planned purchase with a clear need and a repayment plan. The weakest is repeated impulse shopping because financing is available. That difference says more about whether the app will help you than its download count or rating.
My connectivity verdict
After looking at Snap Finance through the lens of real mobile use, I see a focused shopping-finance app that can be convenient when you need to explore a pay-later route and have a dependable connection. Its appeal is strongest for shoppers who may not have traditional credit available and who are willing to examine the repayment responsibility carefully.
The network-dependent nature of the experience is not a deal-breaker, but it changes how I would use it. I would prepare before opening it, avoid unstable connections for important actions, and verify the result after any interruption. Those habits reduce confusion and make the app feel more controlled.
Snap Finance is not a replacement for budgeting, savings, or careful comparison. It is also not the right answer for every purchase or every financial situation. For a necessary item where timing matters and the terms genuinely fit your budget, it can be a useful option. For discretionary spending or an already stretched budget, I would choose a slower, less expensive path instead.
Overall, I would recommend trying it only with a specific purchase in mind and enough time to read everything. The app is free, developed by Snap Finance, and available to users on Android 7.0 and newer, but those conveniences should come after the financial question: can I comfortably meet this commitment? If the answer is clear, the mobile format is practical. If it is uncertain, no amount of connectivity or convenience makes the decision safer.
Frequently Asked Questions
01What is Snap Finance, and how does it work?
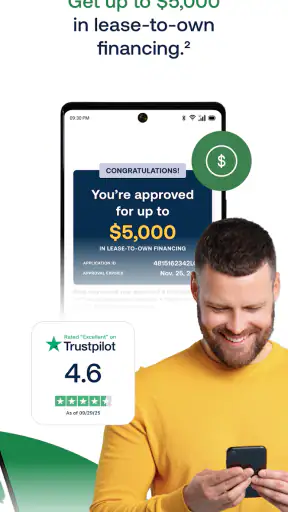
Snap Finance is a lease-to-own financing service that may help eligible customers purchase products when traditional credit approval is difficult. After submitting an application, Snap reviews your information and may provide a spending limit or payment option through participating retailers. You then make scheduled payments under the agreement. Approval, available amount, fees, and terms depend on your application and the specific merchant transaction.
02Does using Snap Finance require good credit?
Snap Finance generally markets its service to shoppers who may not qualify for conventional financing, so a perfect credit score is not always required. However, approval is not guaranteed, and Snap may review information such as your identity, income, banking details, and payment history. Before accepting an offer, carefully check the total cost, payment schedule, renewal conditions, and any applicable fees rather than focusing only on approval.
03How much does Snap Finance cost?
The cost depends on the purchase amount, repayment or lease-to-own structure, payment frequency, and the terms shown in your agreement. The total amount paid can be considerably higher than the original cash price if payments continue for the full term. Some agreements may offer an early purchase option that reduces the overall cost. Always review the disclosures and calculate the total before completing a transaction.
04Can I use Snap Finance with any store or for any purchase?
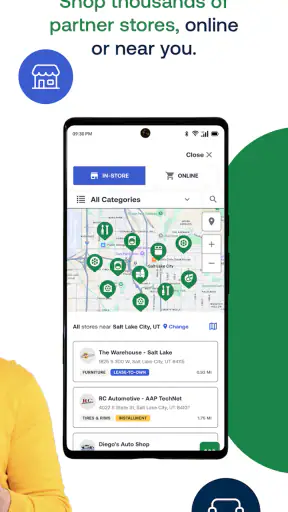
Snap Finance is typically available only through participating retailers and approved merchants, so it cannot necessarily be used everywhere. Product eligibility, minimum purchase amounts, spending limits, and available payment options may vary by store. The app or merchant checkout may show whether financing is available for a particular purchase. Confirm the retailer, product restrictions, and exact agreement terms before relying on Snap for payment.
05Is the Snap Finance app safe, and what information does it require?
The official Snap Finance app or website may request personal and financial information needed to verify your identity, evaluate an application, manage payments, and communicate account updates. Download it only from an official app store or Snap’s verified website, and check the developer name before signing in. Use a strong, unique password and avoid sharing verification codes. Also review the privacy policy and permissions so you understand how your information is handled.


